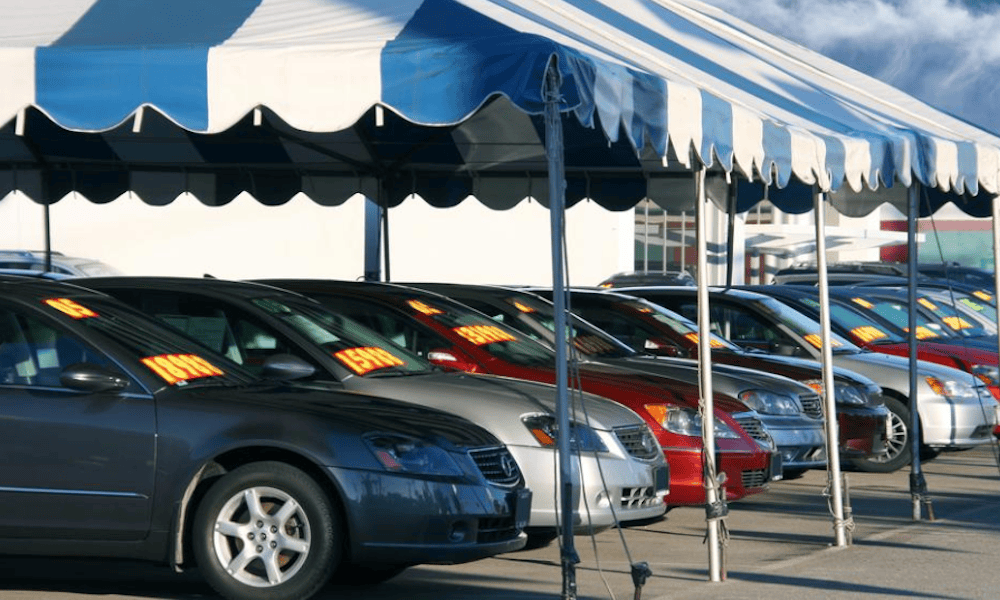
Auto dealerships risk multiple natural disasters, including wind, oods, wildres, hail and earthquakes. Some of these are covered by commercial property insurance, while others require special forms of insurance. All demand attention, because there are many ways gaps can occur. We’ll look at some of the most common and provide you with important questions to discuss with your insurance professional.
Could your business survive major hail damage?
One of the most common large-loss weather-related exposures auto dealerships face is hail. Imagine a major hailstorm doing $4,000 worth of damage to each of your outdoor vehicles. Then imagine that happening again four weeks later to the repaired cars.
What would your deductible be? How much is your aggregate coverage? Are you insured for the loss of value of damaged vehicles? And how about your lost revenue if you have no inventory to sell because it’s all in the shop being repaired, or on the lot awaiting repairs? Can you sell the cars in a hail sale, and if so, what does that do to your insurance payout?
Know what kind of hail coverage your policy includes and how the carrier will pay those claims. Ask about deductibles and exclusions. In some cases, your business property insurance will contain a percentage deductible. For example, if you have $4 million in property coverage, you might have a 5% deductible, meaning you would pay $50,000 on a $1 million loss. Under some policies, you might pay a per-car deductible, which could be a good arrangement for dealers with covered lots but might mean a massive out-of-pocket loss for those without.
Your insurance professional may suggest enhancing your coverage with a parametric insurance policy. These are contracts that dene an event, such as hail of a certain diameter, and pay a set amount if the weather station serving your property measures such an occurrence. No deductibles or adjusters are used. The contract has a metric, and the insurer pays if that metric is recorded.
What if your loss is from a tornado or re that destroys your inventory and your buildings? How are you covered for that kind of total loss? Will your coverage allow you to set up in another location, or must you rebuild on the same lot?
And can you cover salaries while you rebuild? How about employee benets and loans? There’s a lot to think about in a large-loss scenario. Your insurance professional can help you nd a blend of coverages that protect your business from failure. Remember that ood and earthquake losses will have to be insured dierently from other property loss events, such as vandalism, theft and fires.
Cyber theft and fraud
Physical assets aren’t the only items causing large-loss risks. In 2019, as many as 3.1 million pieces of customer data may have become compromised by an attack on dealerships in Australia, Japan, Thailand and Vietnam. A wealth of valuable customer information, including Social Security numbers, credit reports, bank accounts and addresses, can be stored in a dealership’s management system, making it highly attractive to cyber attackers.
Without the right blend of cyber risk and crime insurance, you could be putting your dealership at risk. Remember that not all cybercrime is committed by outsiders. If an employee intentionally releases data or facilitates cybercrime, you may need a delity bond or some other internal crime or embezzlement insurance. Talk to your agent or broker about the specics of both internal crime and cyber hacking so you get comprehensive protection.
Check your liability insurance
Dealerships conduct multiple business operations under one roof: new and used vehicle sales, service, parts and even auto body repairs. If your dealership oers services, additional liability coverage will protect customer vehicles and property under your care at the time of a loss.
If you had 10 $50,000 vehicles left overnight for service and they were torched in a riot or destroyed in a storm, you would likely be sued for the value of the vehicles and anything in them. Your garagekeepers liability coverage would likely respond, but do you know your deductible? What about your coverage limits? Are they adequate for a multicar total loss? If a ood or an earthquake caused the destruction, would you be insured for the property of others in your care?
A drawn-out process
If your large loss is due to a regional or local weather disaster, like a tornado, flood or wildfire, your business could be closed for months or longer. It might be a long time before an adjuster can assess the damage or a contractor can get to you to make repairs.
It’s essential to talk to your insurance professional about gap coverage while you await the insurance payout. Remember that in such widespread catastrophes, the cost of services and materials used to rebuild can also increase. Even the expense to have debris hauled away rises. Such price hikes can push or even exceed your coverage limits.
Without adequate insurance, a large loss can mean the end for an auto dealership. Work with your agent or broker to make sure you have the right coverage for all your major exposures. Also ask your insurance professional about help with your business continuity and risk management plan.
Thinking through a large loss before you have to deal with one in real life can help immensely if such an event occurs. Your in-house sta and insurance professional are all members of your nancial protection team, so work with them to build a comprehensive sustainability program for your auto dealership.