Help Clients Reduce the Scale of Earthquake Devastation With Proper Coverage
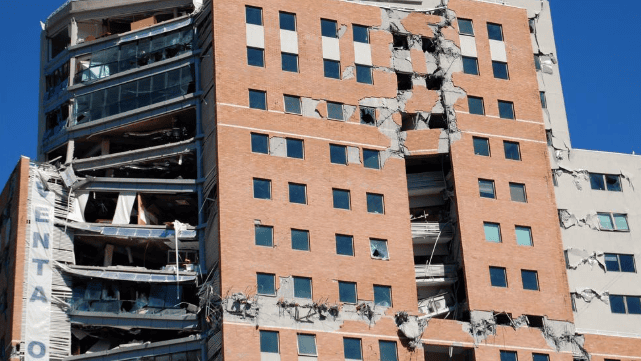
Earthquakes can be incredibly destructive. According to the U.S. Geological Survey, 500,000 earthquakes are detected every year. Of those, about 100 result in measurable damage to people or property. It doesn’t pay to be complacent. Even small quakes can be terrifying, and large quakes can be devastating.
How quickly an area can recover from an earthquake depends on many factors. One of those factors is how extensive the insurance coverage is. Too often, that coverage is inadequate to help people get back on their feet.
For example, the Federal Emergency Management Agency estimates that only 10% of Californians have earthquake coverage. That’s despite the fact that 90% of the earthquakes in the U.S. occur in California.
Part of the problem is that earthquakes are very hard to predict. Although earthquakes tend to run along fault lines, whether a property sits on a fault line is a very weak indicator of risk. Many small earthquakes go undetected. And the effects of other human activities are only now being recognized. For example, fracking can increase earthquake risk by altering subsurface pressure and triggering movement along fault lines. Fracking is a process of extracting oil and natural gas by injecting high-pressure fluid into underground rock to create fractures.
Experts propose that California has experienced an “earthquake drought” over the past 25 years, and U.S. Geological Survey seismologists find this is unlikely to continue. In short, people may be unaware of the extent of the risk and are underestimating the importance of insurance.
While earthquakes cannot be prevented or predicted, our best hope to reduce the scale of the devastation is loss prevention and adequate insurance. Where possible, we must build structures capable of withstanding seismic forces and prepare for the worst. When the worst comes, insurance is the best recourse against a client’s unavoidable losses.
Coverage under homeowners policies
Earthquake damage is generally excluded from coverage. However, if there’s a secondary loss resulting from a fire or an explosion caused by the earthquake, that will be covered. For example, if an earthquake ruptures a gas line and causes a fire, that loss will be covered. And losses due to a collapse following the movement of earth can be included as a named peril in additional coverage.
If your client wants coverage for losses directly related to earthquakes on their homeowners policy, they must add it as an endorsement. Aftershocks that occur within a certain timeframe after the earthquake may be considered part of the same loss event.
Coverage for commercial property
Most property insurance excludes losses associated with earthquakes. However, if the earthquake results in a fire or explosion, that will be covered. Similarly, damage caused by volcanic eruptions and volcanic effusions (mudslides or flooding) is excluded. But if the volcanic eruption causes a fire or breaks building glass, that will be covered.
Again, your clients can obtain coverage by adding various property endorsements for an additional charge. Separate deductibles apply to buildings, personal property within those buildings and personal property in the open. Deductibles are individually calculated for each earthquake.
Make sure your clients understand their coverage
The losses after an earthquake can be catastrophic, and clients may not fully understand the exclusions and restrictions in their insurance policies. Have an open conversation with your clients to ensure they have appropriate earthquake coverage.
This content is for informational purposes only and not for the purpose of providing professional, financial, medical or legal advice. You should contact your licensed professional to obtain advice with respect to any particular issue or problem.
Copyright © 2026 Applied Systems, Inc. All rights reserved.